
Who Does the Rebuilding
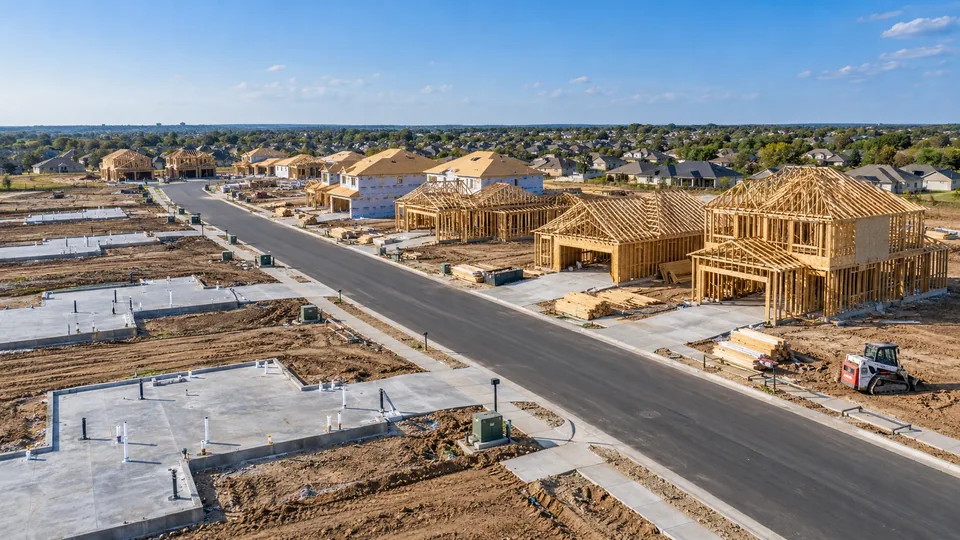
Disaster recovery is usually pictured as homeowners and adjusters, but the construction work runs through contractors and developers: general contractors rebuilding homes and multifamily buildings, developers reassembling lots, civil contractors removing debris and rebuilding roads, storm drains and utilities and specialty trades restoring systems. Each of them carries its own insurance and bond obligations, and those obligations often arrive faster than on a normal project because owners, lenders and agencies want work to start.
Rebuilding homes at volume ties back to residential general contractor insurance.
The Coverage Map for a Rebuild
Most rebuild programs touch the same lines. Builders risk insures the structure while it is under construction. Contractors pollution liability addresses third-party and cleanup exposure from debris, ash and runoff. General liability, often project-specific on larger rebuilds, responds to injury and damage to others. Wrap-ups can fit when one sponsor rebuilds many homes or a large public program. Performance, payment and maintenance bonds secure public and private contracts.
- Builders risk for the new structure, with wildfire, earth movement and flood terms reviewed
- Contractors pollution liability for burn debris, ash and runoff
- Project-specific general liability for larger rebuilds
- Wrap-ups for multi-home or public rebuild programs
- Performance, payment and maintenance bonds for public and private contracts
The property side starts with builders risk for wildfire rebuild projects.
Burn Debris, Ash and Pollution Exposure
Fire debris is not ordinary demolition waste. California's debris programs remove household hazardous waste first and then ash and debris, and contractors that remove debris privately in Los Angeles County needed specific licenses, hazardous substance certification and worker training. A contractor handling burned sites, grading burn scars or working near drainage can face third-party claims and cleanup costs that a general liability policy may exclude, which is why contractors pollution liability is usually central to recovery work.
How that exposure is typically insured is explained in pollution liability for burn debris and ash removal.
Rebuild Permitting Programs Change the Path, Not the Coverage
Recovery programs can speed permitting. After the January 2025 Los Angeles fires, state executive orders suspended CEQA and Coastal Act permits for like-for-like rebuilds within 110 percent of the prior footprint and height, and the City and County of Los Angeles added fee waivers, one-stop centers and self-certification by licensed design professionals. Those programs move the rebuild faster through review, but the insurance a lender or owner requires, and the terms an underwriter sets, still apply.
The Los Angeles programs are set out in detail under coverage for contractors rebuilding in the Palisades and Altadena.
Rebuild Regions We Cover
Rebuild rules are local. Los Angeles County's 2025 fires brought the largest set of recovery programs in the state. Southern California mountain and foothill communities rebuilding after the 2024 Line, Bridge, Airport and Mountain fires face wildland-urban interface construction rules and steep terrain. Northern California towns such as Paradise continue to rebuild years after the Camp Fire, and the Texas Hill Country is rebuilding after the July 2025 floods under county and city floodplain rules.
- Los Angeles County: Palisades, Eaton and other January 2025 fires
- Southern California mountain and foothill communities, including cabin areas
- Northern California fire rebuilds, from Paradise to the Sierra foothills
- Texas Hill Country flood rebuilds, centered on Kerr County
For cabin and mountain communities, see coverage for mountain cabin and foothill rebuilds.
Bonds for Recovery and Repair Contracts
Public agencies rebuilding roads, storm drains, debris basins and utilities typically still require performance and payment bonds on construction contracts, and cities and counties continue to require improvement and encroachment security for work in their right of way. A contractor taking on recovery work usually needs its bonding capacity and financial statements ready before the bid, since recovery programs can produce several contracts in a short period.
The bond thresholds by state are explained under public works bond requirements.
Licensing and Pricing Rules in Declared Disasters
Declared disasters bring extra rules for contractors. In California, the Contractors State License Board warns that contracting without a license in a declared disaster area is a felony, and the Attorney General explains that Penal Code 396 limits price increases after an emergency declaration, including for reconstruction and cleanup services. Texas has its own disaster-period pricing rules. Working within those rules protects the contractor as much as the owner.
Before You Ask for a Quote
What to Gather
- Rebuild contracts and each owner's lender insurance requirements
- The permit path for each site (like-for-like, self-certification or standard)
- Debris removal status and soil testing results for each lot
- Your current GL, pollution and builders risk forms with every endorsement
- Subcontractor licenses and certificates
What to Ask the Insurer or Surety
- Will builders risk be written for the wildfire or flood peril at these sites, and on what terms?
- Does our general liability exclude pollution from debris, ash or runoff?
- Would a wrap-up fit a multi-home rebuild program?
- Which bonds will public recovery contracts require?
Quick Answer
Rebuilding after a wildfire or flood typically calls for builders risk on the new structure, contractors pollution liability for debris and ash, general liability (often project-specific) and bonds for public and private contracts. Local rebuild programs change permitting, not what the policies and bonds require.
Common Mistake
Treating fire debris and grading on a burn scar like ordinary site work. Ash, asbestos and runoff can fall outside a general liability policy, so pollution coverage is checked before work starts.
Broker Perspective
We start with the permit path and the lender's requirements for each site, then confirm which carriers will write the property and pollution exposure in that area.
Coverage Impact
Coverage depends on the forms and endorsements issued; wildfire, earth movement and flood terms vary widely in builders risk, and pollution exclusions vary in general liability.
Questions Buyers Ask
Do rebuild permit programs change the insurance a lender requires?
Usually not. Like-for-like and self-certification programs change the permitting path, but lenders and owners typically keep their insurance requirements, including builders risk and liability terms.
Why is pollution coverage important for fire rebuild work?
Burn debris can contain ash, asbestos and other hazardous material, and grading and runoff on burn scars can affect neighbors and drainage. Many general liability policies exclude pollution, so a contractors pollution policy is typically part of the program.
Can a wrap-up cover a multi-home rebuild?
It can, when one sponsor rebuilds enough homes or a large public program to justify the administration. Smaller rebuilds usually rely on each contractor's own program.
Are there special contractor rules in declared disaster areas?
Yes. In California, contracting without a license in a declared disaster area is a felony, and Penal Code 396 limits price increases for reconstruction and cleanup after an emergency declaration.
Official Sources
- Executive Order N-20-25 (state permitting and housing laws for the January 2025 fires), Office of the Governor of California. Covers seven January 2025 fires in Los Angeles and Ventura counties; limits the rebuild suspensions to like-for-like work within 110 percent of the prior footprint and height; extends permit terms and lets agencies accept same-design rebuilds. Verified 2026-10-25.
- Like-for-like rebuild, County of Los Angeles. Defines a like-for-like rebuild in unincorporated areas by size, location and use, with limited expansion, built to current building, fire and health codes. Verified 2026-10-25.
- Disaster debris removal: contractor requirements (2025), Contractors State License Board. Debris removal permits go to contractors holding the Hazardous Substance Removal Certification with an A, B or C-12 and C-21 license; workers need 40-hour HAZWOPER training. Verified 2026-10-25.
- Disaster information for contractors and consumers, Contractors State License Board. Contracting without a license in a declared disaster area is a felony. Verified 2026-10-25.
- Price gouging during states of emergency, California Attorney General. Penal Code 396 bars price increases of more than 10 percent after an emergency declaration, including reconstruction and cleanup services for 180 days. Verified 2026-10-25.
- Flood damage permitting guide, Kerr County. A floodplain permit is required for structures touching Zone A, AE or the floodway, even for repairs or demolition; Kerrville and Ingram use their own floodplain administrators. Verified 2026-10-25.
Reviewed by the Principal, Gleason Insurance Brokers, LLCUpdated

